
Summary
ConocoPhillips reported second-quarter 2018 earnings of $1.640 billion, or $1.39 per share, compared with first-quarter 2017 earnings loss of $3.44 billion, or $2.43 per share.
Oil equivalent production was 1,249K Boe/d in the second quarter down 13.1% from a year ago and down 1.6% sequentially.
The company plans plan to increase its shares buyback this year to $3 billion.
While I believe COP is an excellent long-term choice, I recommend trading about 30%-40% of your holding based on the technical analysis to pinpoint overbought and oversold situations.
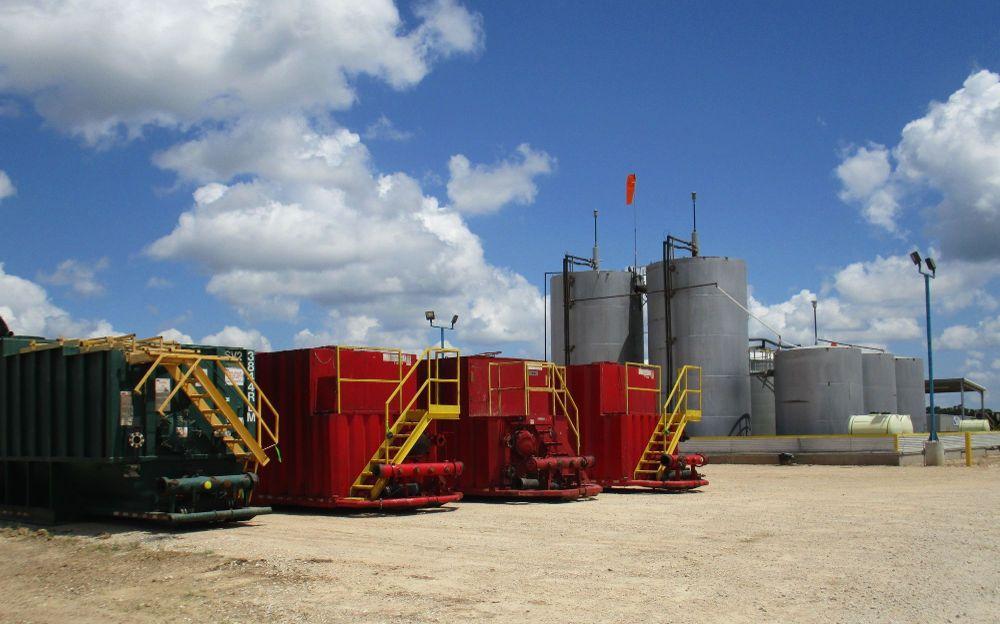
Image: ConocoPhillips facility in Eagle Ford.
Investment Thesis
ConocoPhillips (COP) is an oil company that I like mainly because of its substantial assets portfolio and projects pipeline.
The potential for steady profit is quite apparent, given the robust future growth and the likelihood of a further increase of shareholder dividend in 2018, primarily with oil prices climbing well over $70 a barrel.

