
Summary
- Parsley had a pretty good Q1 with solid cost and production performance.
- It is still expected to have some cash burn in 2019 at current strip prices, as it is growing production by a decent amount.
- Parsley appears slightly undervalued based on the current oil price environment.
- Cash flow may turn slightly positive in the second half of 2019 with perhaps 55% of full-year capex coming in the first half.
- Looking for a community to discuss ideas with? Distressed Value Investing features a chat room of like-minded investors sharing investing ideas and strategies. Get started today »
Parsley Energy (PE) has been delivering according to its 2019 expectations so far and had a good Q1 in terms of cost and oil production. It will burn some cash in 2019 at current strip prices while carrying out its production growth plans, but may be able to reach positive cash flow in the latter part of 2019.
I believe that Parsley is slightly undervalued in the current oil price environment and should be worth a bit over $20 per share.
Q1 2019 Results
Parsley's results in Q1 2019 were pretty good, with its oil production averaging approximately 78,911 barrels per day. This was above its expectations for Q1 oil production ranging from 75,500 to 78,000 barrels per day.
As well, the company managed to keep its lease operating costs low at $3.65 per BOE. While this is slightly higher than its $3.61 per BOE average from 2018, it is also towards the low end of its $3.50 to $4.50 per BOE guidance range for 2019, and leads to the expectation that Parsley can hit the lower half of that range for the full year.
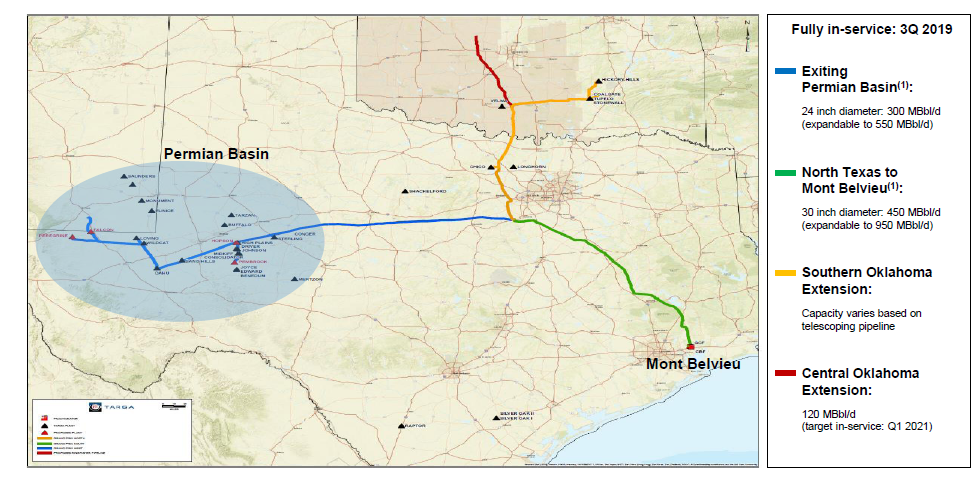
On the negative side, Parsley realised $17.97 per barrel for its NGLs during Q1 2019, down from $25.00 per barrel in Q4 2018. The Q3 2019 completion of Targa's Grand Prix NGL pipeline should help with NGL realisations later in the year though.
Source: Targa Resources
2019 Projections For Parsley
With $57 WTI oil and relatively weak prices for NGLs in 2019, Parsley may end up with around $1.88 billion in oil and gas revenues before hedges and $1.833 billion in revenues after hedges.
Parsley's hedges are largely designed so that it can benefit from oil prices going up, with the cost being the premiums for its put protection.
| Type | Units | $/Unit | $ Million |
| Oil (Barrels) | 30,112,500 | $55.00 | $1,656 |
| NGLs (Barrels) | 10,013,775 | $18.00 | $180 |
| Natural Gas (MCF) | 41,752,350 | $1.05 | $44 |
| Hedge Value | -$47 | ||
| Total Revenue | $1,833 |
| $ Million | |
| Lease Operating Expense | $177 |
| Production and Ad Valorem Taxes | $122 |
| Cash G&A | $141 |
| Cash Interest | $123 |
| Capital Expenditures | $1,450 |
| Total Expenses | $2,013 |
Thus Parsley would now be expected to end up with around $180 million in cash burn in 2019 along with a decent amount of production growth. This is well within Parsley's goal of limiting its outspend to less than $250 million in any oil price environment.

