
Summary
- Fossil’s Q1 report was ugly, with accelerating sales decline standing out as the greatest concern.
- A leaner balance sheet, focus on wearables, and a partnership with Google are not likely to revive an antique business model.
- Wearables sales are already falling, inspiring little hope for a pivot toward a more robust segment.
- Near-term outlook is price-neutral and volatility-bullish, but we expect Fossil to underperform long term.
Fossil's (NASDAQ:FOSL) 2019 outlook has gone from uncertain to dismal, along with its prospects for the foreseeable future. At the beginning of the year, one could be forgiven for venturing cautious optimism. Though Q4 disappointed the market, it was encouraging to see $50 million in profits following nearly two years of quarterly losses. Continued development of the Wearables segment and a mysterious IP deal with Google (NASDAQ:GOOG) (NASDAQ:GOOGL) represented digital lifeboat for a vintage ship. As it undertook aggressive measures to reduce costs, the company seemed headed toward modest profitability, a manageable sales decline, and leadership in an emerging segment.
These hopes were dashed after Q1 offered virtually nothing to encourage this narrative. Sales in nearly all categories, including wearables, continue to fall at an accelerating rate. Twelve month trailing (TTM) sales have fallen 30% since 2015 highs. Since that time, net losses have steadily eaten into retained earnings, which fell from over $1.3 billion to $340 million in just a few years. We feel that, given these facts, the stock's current valuation is fair to high for the company, and that there is little to entice a long-term investor unless more encouraging data comes in. We also expect high price volatility in the near term.
Strategic Pivots Have Failed
In the name of profitability, the company has undergone a major effort to restructure its business, axing over 40% of its locations since 2015, and downsizing its product line in favor of proven performers. This succeeded in reducing SG&A expense and slightly improving gross margins. Unfortunately, gross profit continues to plummet as sales go off a cliff. Since 2015, SG&A fell roughly 17% against a fall in gross profit of 35%. Despite management's best efforts to depict a leaner, more competitive company, the hard truth is that the decision to scale down will not save Fossil.
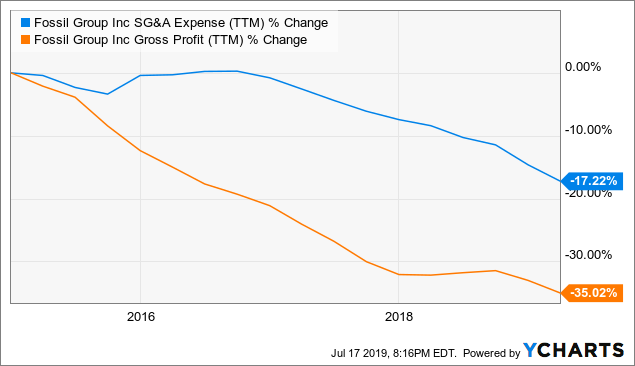 Data by YCharts
Gross Profit Decline has Outpaced SG&A Cuts
Sales Across The Board: Mayday
Fossil's top line is crashing at an impressive speed. Since 2015, the company has seen negative YoY sales growth in every quarter, with the rate accelerating to its highest point ever last quarter: 18%. All four relevant segments (Watches, Wearables, Leathers and Jewelry) experienced double-digit decline.
The company's two major markets, the Americas and Europe, comprise roughly 75% of sales. In Q1, these two markets saw sales decline 23% and 24%, respectively. The Asian markets received some positive attention in the company's earnings call, simply for maintaining flat sales year over year.
The consistency of sales decline, as well as the fact that sales appear to be falling ever more rapidly, is impossible to ignore. Wearables are perhaps the only reason to give this company a second look at this point, and the numbers don't look any better.

