
Summary
- ConocoPhillips reported Q2-2019 earnings on Tuesday that slightly missed profit estimates.
- Regardless, COP was soundly profitable in terms of both earnings and cash flow.
- I see considerable downside risks for COP as the company has a below-average diversification profile and the trade conflict just erupted again.
- An investment in COP yields 2.1 percent.
ConocoPhillips (COP) reported slightly worse-than-expected second-quarter earnings on Tuesday. Despite a decrease in year-over-year price realizations, ConocoPhillips was solidly profitable in the second quarter. Due to below-average business diversification, however, I see considerable downside risks for COP ahead, especially if the trade war between the U.S. and China further escalates.
ConocoPhillips - Second Quarter Earnings Review
ConocoPhillips reported $1.1 billion in second-quarter adjusted profits on July 30, 2019 compared to $1.3 billion in the second quarter a year ago. On a per-share basis, ConocoPhillips said it earned $1.01/share, which was down ~7 percent from $1.09/share in the same period last year. Analysts expected ConocoPhillips to report adjusted profits of $1.03/share.
A major driver of lower profits in Q2-2019 was a decrease in price realizations. The average realized price of a barrel of oil equivalent was $50.50/bbl compared to $54.32/bbl a year ago, reflecting a decline of ~7 percent.
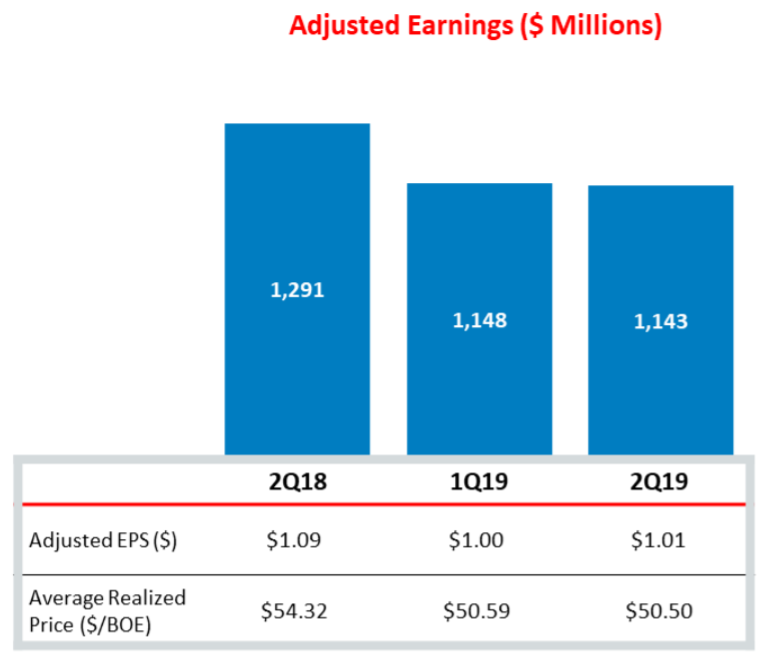 Source: ConocoPhillips Investor Presentation
Despite the decline in price realizations, ConocoPhillips was soundly profitable in the second quarter in terms of both earnings and free cash flow. ConocoPhillips pulled in $1.7 billion in free cash flow in the second quarter compared to $1.3 billion in FCF in the first quarter. The energy company easily covered its capital returns (dividends and share buybacks) which amounted to $1.5 billion, or 47 percent of ConocoPhillips' operating cash flow.

