
Summary
- Phillips 66 posted second quarter 2019 earnings of $1,422 million or $3.12 per share beating expectations again. Adjusted earnings were $3.02 per share, a big jump from 1Q'19.
- During the quarter, Phillips 66 returned a total of $861 million to shareholders through $406 million of dividends and $455 million of share repurchases.
- PSX is a secure stock with a good profile from a long-term investor's perspective. However, I recommend trading the short term with about 30% of your position.
Source: The Street/Bloomberg
Investment Thesis
Houston, Texas-based Phillips 66 (PSX) is a large US refiner stock and it ought to be owned as a long-term investment in any savvy investor's portfolio, even if I am noticing some fundamental weaknesses rooted deeply in the company business model that I will try to explain in my article.
Phillips 66 is one of the world’s largest downstream oil corporations in this "refiners" segment. For the investors interested in this particular segment, I recommend following the VanEck Vectors Oil Refiners ETF (NYSEARCA:CRAK) which has outperformed the three refiners that I am analyzing on Seeking Alpha.
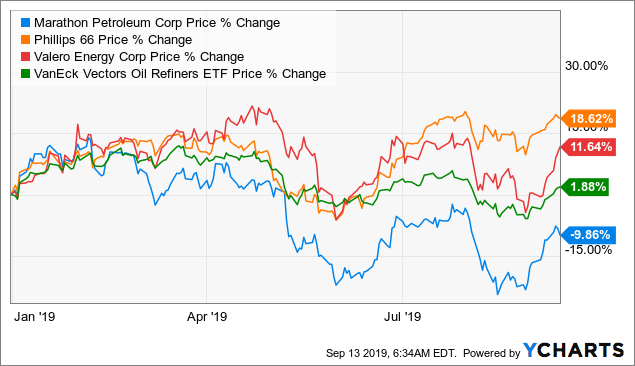
In term of revenues versus net income, Phillips 66 fared a little better this quarter than its peers, if we compare to Valero (VLO) or Marathon Petroleum (MPC).

