
Summary
- As far as the oil patch goes, few companies, if any, can match the opportunities offered by ConocoPhillips.
- Management's just-announced 10-year plan highlights significant prospects for shareholders.
- This proves, yet again, why it's a really amazing company in its space.
- Looking for a helping hand in the market? Members of Crude Value Insights get exclusive ideas and guidance to navigate any climate. Get started today »
At this time, ConocoPhillips (COP) is one of the largest oil and gas E&P (exploration and production) firms on the market. Given its size and experience in the space, the company has done well to see what the future might have in store for the industry and to position it optimally. Every so often, management releases some sort of near-term guidance that gives a hint as to what they think that might be, but, on November 19th, the company revealed a long-term plan taking its thinking out to 2029. Though bold, the measure is appreciated and it gives shareholders not only a degree of confidence but a look as to what will also be the value drivers for the firm over the next several years.
Big plans create big returns
One common theme among many of the oil and gas E&P firms right now is an emphasis on the Permian Basin. It's a hot area due not only to drilling prospects but also because of what it is geographically located. Other big players like Exxon Mobil (XOM) and Chevron (CVX) have, over the past year or so, made major commitments to the region, viewing it as a key part of their growth plans. This outcome will likely be more or less positive for the firms taking the dive into the Permian, but in its own investor presentation, ConocoPhillips proved that it's not the only viable way forward.
Over the 2020 through 2029 timeframe, the energy giant has what I would call a three-pronged approach to its business model: milk its APME (Asia Pacific, Middle East) region for the cash it can, grow production in the US, and grow production in its Alaska, Canada, and Europe business. In its APME region, the company intends to invest very little over time, instead opting to let production drop modestly. During this timeframe, though, the low decline rates associated with those assets will generate free cash flow for the business of about $15 billion at current energy pricing.
Source: ConocoPhillips
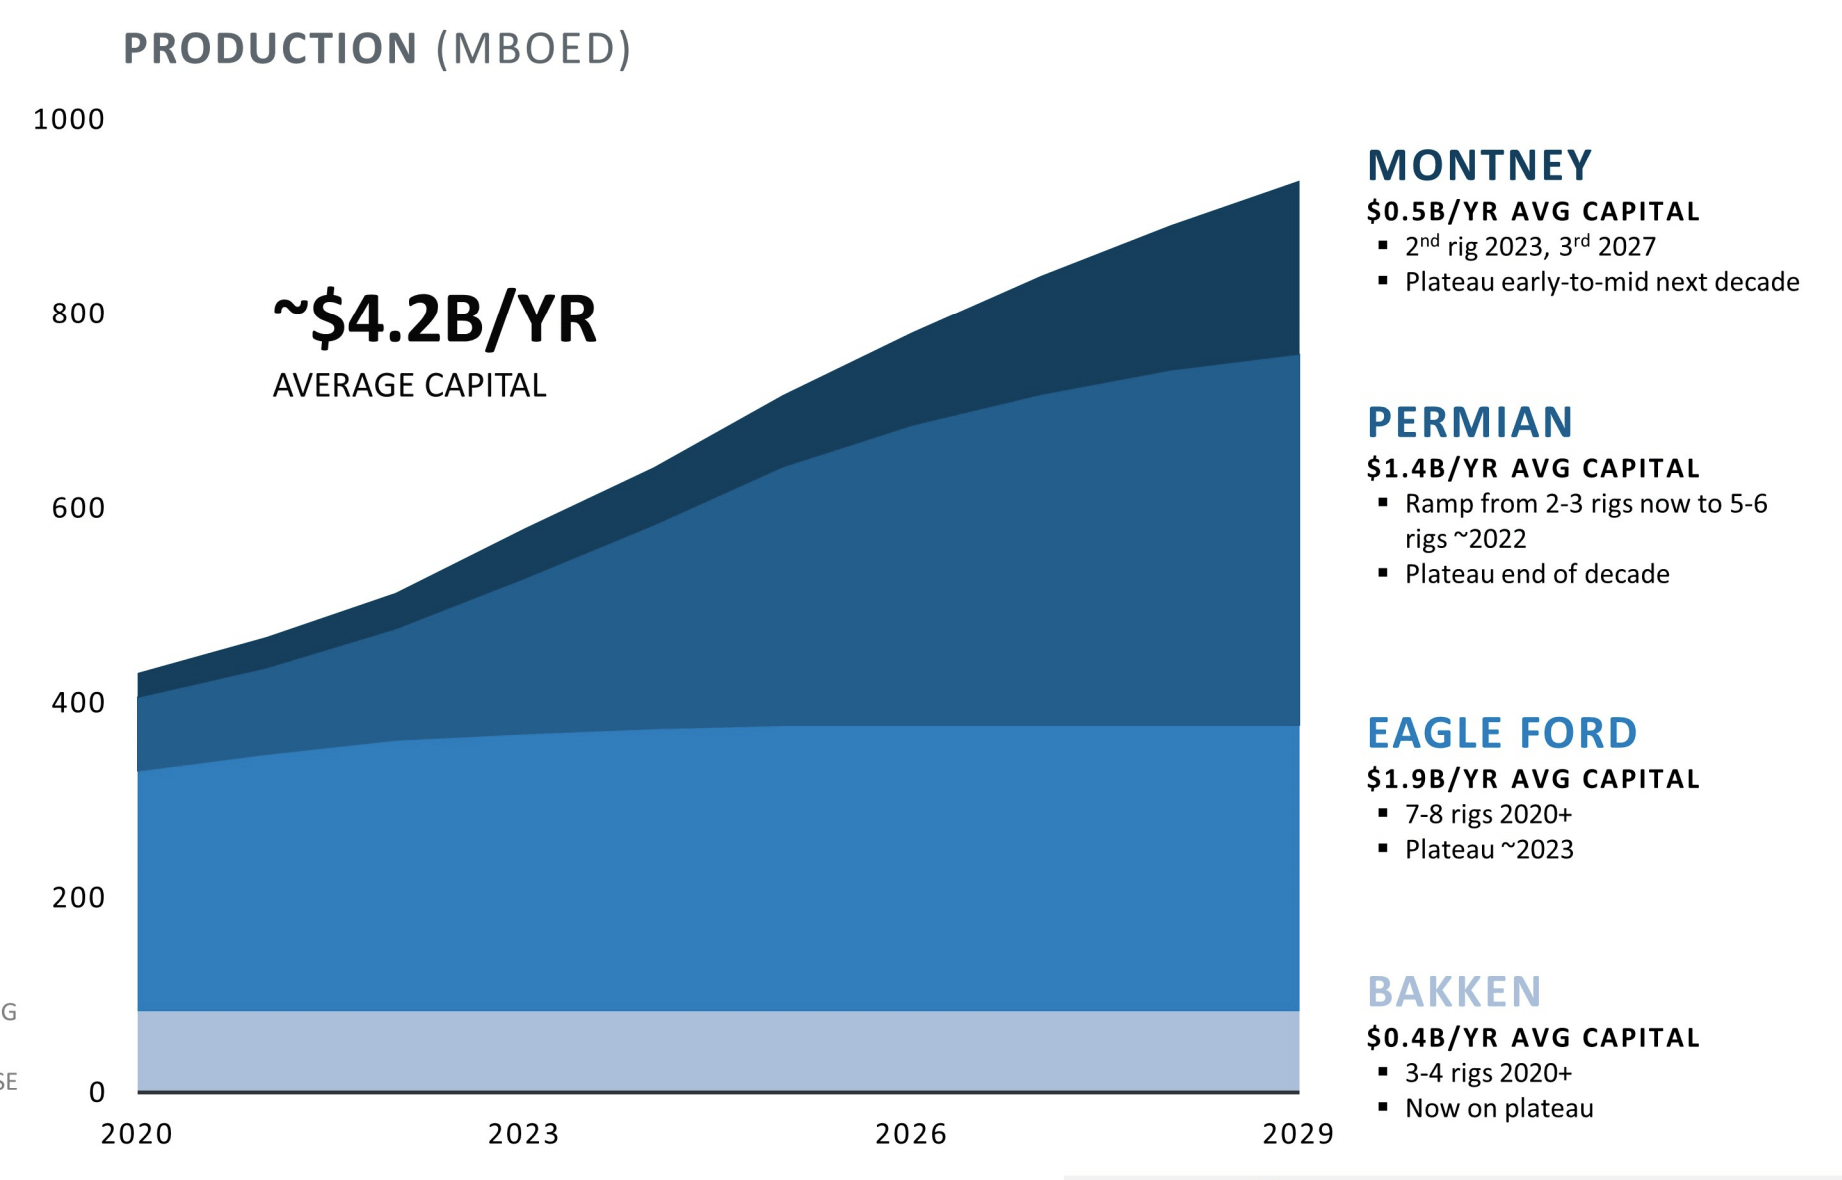
In the US (specified as the Lower 48), the picture is entirely different. According to management, it wants output here to rise considerably, growing from around 450 thousand boe (barrels of oil equivalent) per day to around 800 thousand boe per day. For most companies in the US today, the Permian Basin is a huge source of activity and opportunity, but that's only a small piece of the pie as far as ConocoPhillips is concerned. Between 2020 and 2029, the company wants to invest, on average, about $4.2 billion in cash per year in the development of its unconventional assets. Of this, about $1.4 billion per annum will be dedicated to the Permian. Over the 10 years covered, this will result in excess free cash flow for the firm of about $4 billion.

