
Summary
- I believe the $7-8 EPS FY21 target is achievable.
- The strong Q4 and FY20 guidance indicates the FY21 targets are within reach.
- Transformation into a tech solutions provider to drive longer-term upside.
Recent corporate action, such as the deal to sell its energy, chemicals and resources (ECR) unit to WorleyParsons, supports the case for the ongoing transformation at Jacobs Engineering (JEC). With the unlocked capital post-ECR sale, JEC is well-positioned to initiate repurchases, while driving cost synergies in an effort to hit the $7-8 EPS number by FY21. I think the number is achievable and if JEC gets there, an earnings multiple in line with historical numbers would bring the stock up to ~$105, with the prospect for further upside if the market assigns a premium multiple to account for JEC's transformation.
Encouraging Q4 Validates the Bull Case
Though the focus in recent months has been squarely on the company's strategic actions, JEC’s strong Q4 was a nice reminder of the resilience of the core business model, as the company saw broad-based improvement across both revenue and profitability.
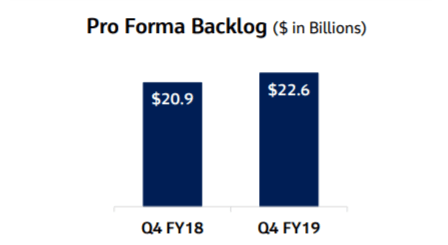
Overall backlog reached $22.6B (+13.1% YoY), driven by strength across the People & Places Solutions segment backlog at $14.1B (+9.9% YoY) and Critical Mission Solutions (NYSE:CMS), with $8.5B (+19.2%). This brought pro forma book-to-bill up to 1.05x for Q4.
Source: Jacobs Engineering Q4 Results
The strong backlog numbers filtered through to group sales as well, which reached $3.3B, while adjusted operating profits hit $253M on margins of 7.5%, the highest level over the past year. The People & Places Solutions segment remains the key contributor to operating profits, posting a ~9.5% margin (+40bps expansion), while CMS segment sales of $1.3B translated to margins of 6.7% (+15bps expansion).

Source: Jacobs Engineering Q4 Results
The company's gross margins tend to be negatively impacted by larger contracts and procurement-related revenue (generally low-risk work which carries a lower gross margin). In Q4, though, management drove operating leverage (G&A expenses fell 75bps YoY) with cost control initiatives and the realization of cost synergies from recent acquisitions (CH2M and KeyW).
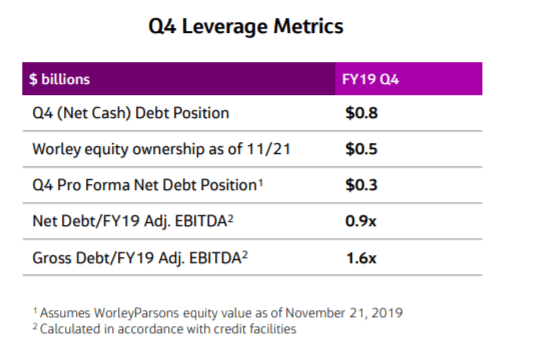
JEC also has a strong balance sheet - as at Q4, the company sits on $630M of cash and equivalents, and gross debt of $1.4B (net debt of ~$0.8B). Gearing ratios also seem manageable - net debt to adjusted EBITDA stands at 0.9x as at quarter-end.
Source: Jacobs Engineering Q4 Results
JEC's balance sheet flexibility means it is able to consistently return capital to shareholders, with $23M in cash dividends and ~$850M in repurchases in FY19 (~$400M remaining under the current repurchase authorization).

