
Summary
- PLAY has been languishing for months in the $40s and below.
- While PLAY is not perfect, I think the stock has fallen far too much.
- Based on what I think are too-low expectations, PLAY is a buy.
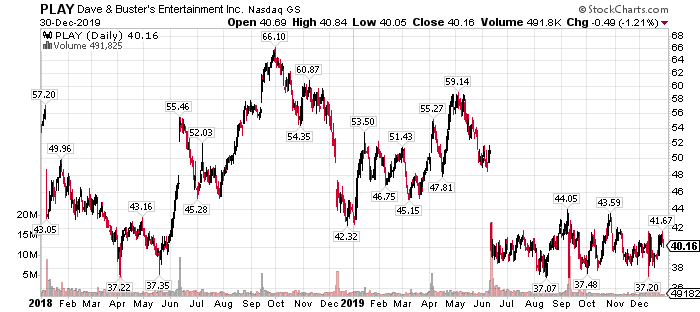
Dave & Buster's (PLAY) has a unique combination of entertainment and food/drink that has worked very well for it in the past. I've been bullish on PLAY at various times since it came public because the stock tends to overreact in both directions, with that oscillation producing some very cheap valuations at times. As you can see below, since cratering in June, shares have spent the past several months bouncing between $37 and $44, with the current price almost right in the middle of that range. I think the company's woes are real, but also that they are priced into the stock, and then some. As a result, I still think PLAY is a buy on a valuation basis.
This isn't the PLAY of old
PLAY used to produce some truly heroic revenue growth numbers. The company was opening stores at a quick rate and getting them up to speed very quickly in terms of volumes. In addition, comparable sales added their fuel to the fire, resulting in what can only be described as outstanding growth below.
Note: revenue is in millions of dollars.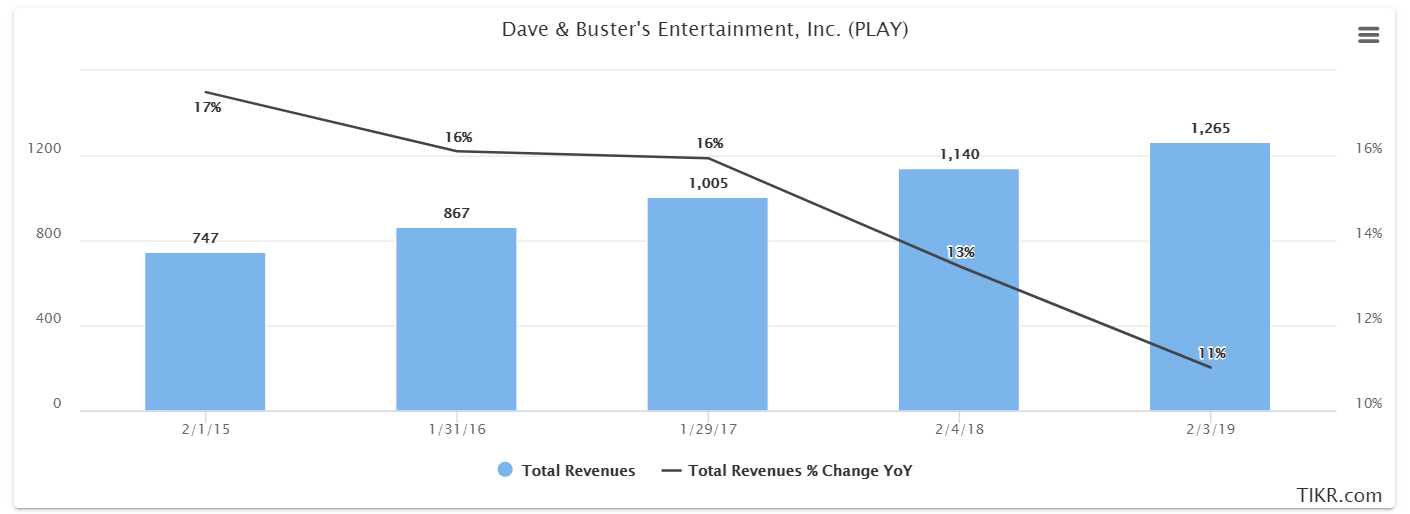
Source: TIKR.com
The company produced 16%+ revenue growth in fiscal 2015, 2016 and 2017, and still maintained double-digit growth in each of the past two years. However, those days are gone as PLAY is a much more mature chain with more locations, and weaker comparable sales. That combination has sunk revenue growth and unfortunately, has weighed heavily on investor sentiment.
The company guided for about 7% revenue growth this year during the Q3 report, which is what analysts have as consensus today. That sounds nice, but the problem is that the company is also opening 16 new stores this year, with 11 of those being the legacy, larger size, and the balance in the new smaller format. That amounts to unit growth of about 12%, so you'd expect revenue to grow something like 10% to account for the larger footprint, as well as the timing of new stores opening up. However, we know that revenue is only to grow about 7%. The difference is due to some pretty awful comparable sales, which are currently forecast to fall between 2.5% and 3.0% this year. That's where PLAY is suffering this year and why the company's shares have fallen as much as they have.

