
Summary
- Etsy delivered explosive growth in the second quarter of 2020.
- The long term bullish thesis for Etsy is stronger than ever.
- Valuation is very reasonable for such a dynamic growth stock.
- A position in Etsy is not without risk, but the upside potential should more than compensate for such a risk.
- I do much more than just articles at The Data Driven Investor: Members get access to model portfolios, regular updates, a chat room, and more. Get started today »
Etsy (ETSY) delivered spectacular numbers for the second quarter of 2020, with the business gaining traction across the board and making significant progress both financially and operationally. The stock is on fire lately, but Etsy still offers plenty of upside potential from current valuation levels.
Etsy Is Firing On All Cylinders
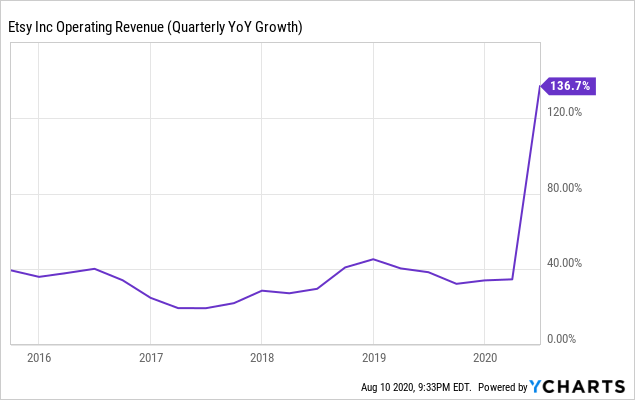
Etsy delivered a year over year increase of 137% in revenue during the second quarter of 2020, to $428.7 million. Marketplace revenue grew 146% and services revenue increased by 110.7%. GMS grew 147% versus the same quarter in the prior year.

Source: Etsy
Growth has significantly accelerated lately, but even before the pandemic, the company was producing consistently strong revenue growth rates. Much of the acceleration in growth is obviously temporary, but there are also some permanent drivers to consider.
All the new buyers and sellers, as well as the existing members who get more engaged with the platform during the pandemic are making the company stronger over the long term, even if growth rates can be expected to decelerate when the economy normalizes.
Consolidated active buyers grew 41.0% year-over-year in the second quarter, and active sellers grew 34.6%. Etsy marketplace's GMS per active buyer on a trailing 12-month basis grew 5% year-over-year and 6% excluding masks, so engagement trends are clearly moving in the right direction.

